Chaperone Health Insurance Plus
Insurance Questions Answered by an Independent Insurance Advisor Near You in Fort Lauderdale
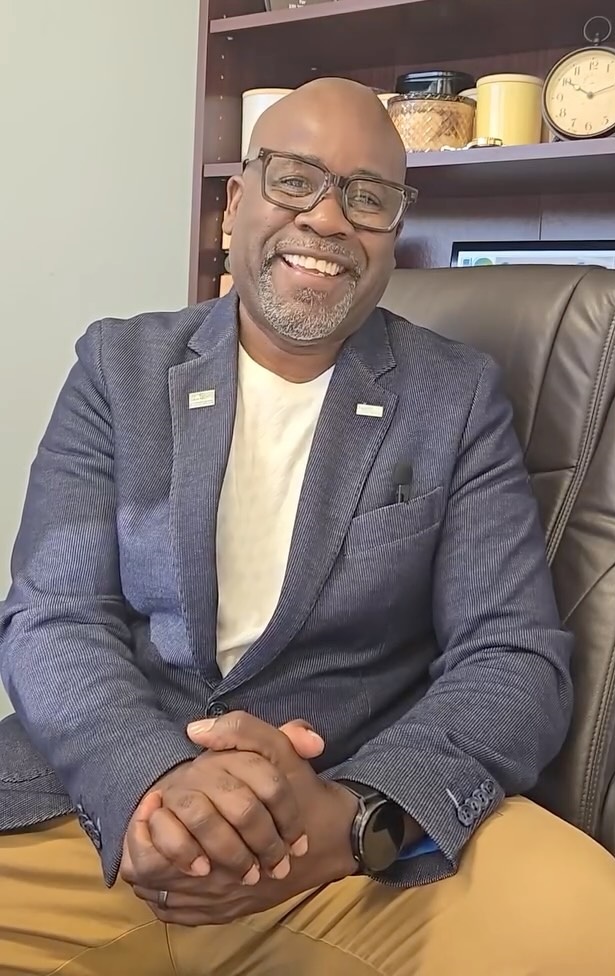
Most people only learn how their insurance works when something goes wrong: a doctor who turns out to be out of network, a prescription that costs more than expected, or an enrollment deadline that passed without anyone mentioning it. I’m Roxroy Ashley, an independent licensed agent with HealthMarkets and the owner of Chaperone Health Insurance Plus, a Black-owned agency in Fort Lauderdale. I’ve spent 14 years in insurance, and I built this Knowledge Center to answer the insurance questions my clients ask most, in plain language, across every kind of coverage I help with.
The guides are organized by what you’re dealing with: Medicare, health insurance for people under 65, turning 65 or retiring, coverage for a small business, and dental, vision, life, and supplemental plans. Each guide covers one decision or deadline, shows the plan year it covers, and is reviewed when the rules change. When you’d like to talk through your own situation, book a free plan review and I’ll get back to you personally within 24 to 48 hours.
LEARN AT YOUR OWN PACE
Get a Free Quote From an Independent Broker With Health Insurance Explained Simply
These guides help you understand your options. When you’re ready for answers about your own coverage, I check:
- Your doctors and hospitals against each plan’s network, including HCA Florida, Memorial, and Baptist Health
- Your prescriptions and pharmacy against each drug list
- Your full-year cost, not only the premium
If anything is unclear, I call your doctor’s office to confirm it. Your quote is free, with no obligation to enroll. Get your free quote and I’ll do the research for you.
Hear how I help you choose a plan with confidence.
MORE THAN A FREE QUOTE
Why Choose Me to Explain Your Insurance Options
When you’re choosing where to learn about insurance, and who to call when you’re ready, here’s what to look for, and what you can expect from me.
Education First, in Plain Language: These guides are written the way I explain things to clients. My goal is for you to understand your options, not just pick a plan name off a list.
Reviewed for Accuracy: Insurance rules, deadlines, and figures change every year. Each guide shows the plan year it covers, and I update guides when the rules change.
Your Doctors, Hospitals, and Prescriptions Checked First: Reading is the first step. When you’re ready for answers about your own coverage, I check your doctors, hospitals, and every prescription against each plan’s network and drug list, including your pharmacy. If something is unclear, I’ll call your doctor’s office myself.
Every Question Answered, at Your Pace: Insurance has a lot of moving parts, and most people spend less than an hour choosing a plan. I take as long as you need, explain each piece in plain language, and answer every question until it makes sense. There’s no pressure and no obligation to enroll.
The Plan That Costs Less for You: The lowest premium isn’t always the lowest cost. I calculate your full-year cost for every plan, including copays, drug costs, and your out-of-pocket maximum, based on your health needs, before you choose.
My Help Costs You Nothing Extra: Insurers pay my commission, and plan premiums are generally the same whether you enroll through me or directly, so you get personal guidance and ongoing support at no additional charge.
One Agent for Every Stage of Life: Medicare, Marketplace plans, small business coverage, and dental, vision, life, and supplemental insurance each work differently. I lay out every path that fits your household and explain what you’d gain and give up with each, so you decide with the full picture.
I Handle the Paperwork: If you choose a plan, I complete the application with you, confirm your enrollment window, and follow it through to approval, so the process is as simple as a conversation.
Licensed and Verified: I’m licensed in 33 states, registered with the federal Health Insurance Marketplace, I complete AHIP’s annual Medicare certification, and I’m certified for the 2027 plan year. You can verify my license (Florida License #W323530, NPN #17946070) anytime through your state’s insurance department.
I Stay Your Agent After You Enroll: Work with me directly, in person, by phone, on Zoom, or at your home in Broward, Miami-Dade, or Palm Beach, and I reply within 24 to 48 hours. I review your coverage every year and help with claims and billing in between.
You can read all 25 reasons we should work together on my Why Choose Me page.
How Does Health Insurance Work? Start Here
If you’re new to any of this, start with the basics. Every health plan, whether it’s Medicare, a Marketplace plan, or a group plan through work, is built from the same pieces. A premium is what you pay each month to keep the plan. A deductible is what you pay for care before the plan starts sharing the cost. Copays and coinsurance are your share of each visit or prescription after that. The out-of-pocket maximum is the most you’d pay for covered care in a year. And the network is the list of doctors, hospitals, and pharmacies the plan has agreed to work with.
Understanding health insurance mostly comes down to seeing how those pieces fit together for the care you actually use. A plan with the lowest premium can cost the most over a year if your doctor isn’t in its network or your medication sits on a high tier. That’s why every guide here, and every plan review I do, comes back to the same three checks: your doctors, your prescriptions, and your full-year cost. Once you have the health insurance basics down, pick the section below that matches your situation.
Medicare Questions: Plans, Enrollment, and Costs
Medicare has its own rules, deadlines, and plan types, so it has its own section. The Medicare Knowledge Center holds 16 guides on the Medicare questions I hear most, grouped by topic:
Enrollment and timing: a Turning 65 Medicare Checklist, how to apply for Medicare online, the CMS-L564 and CMS-40B forms for people working past 65, and COBRA and Medicare.
Plan comparisons: Medicare Advantage vs. Medicare Supplement, Plan G vs. Plan N, and HMO vs. PPO.
Costs: what Medicare Supplement insurance costs, 2027 Part D costs, and IRMAA and Medicare planning for people whose income affects their premiums.
This fall: the Annual Enrollment Period runs October 15 to December 7, 2026, for 2027 coverage. Start with the 2027 Medicare Open Enrollment Checklist and the guide to 2027 Medicare Advantage changes in South Florida.
For plan details and how I help, see my Medicare overview, and my pages on Medicare Advantage, Medicare Supplement, and Part D.
Health Insurance Under 65: Marketplace and Off-Marketplace Plans
If you’re under 65 and buying your own coverage, you’re choosing between ACA Marketplace plans on HealthCare.gov, which may come with financial help based on your household income and size, and off-Marketplace plans, which follow the same core rules but don’t qualify for that help. Both come in metal levels, Bronze through Gold and sometimes Platinum, which describe how you and the plan share costs, not the quality of care.
The deadlines matter here too. Open Enrollment for 2027 coverage runs November 1, 2026, through January 15, 2027, and choosing a plan by December 15, 2026, gets you coverage that starts January 1. Outside that window, a life change such as losing job coverage, moving, getting married, or having a baby usually opens a 60-day Special Enrollment Period.
Guides I’m writing for this section: how Marketplace financial help works, how to choose a metal level, what to do when you lose employer coverage, coverage for a spouse under 65 when the other spouse is on Medicare, and turning 26 and leaving a parent’s plan. Until they’re published, my Individual and Family Health page covers the essentials.
Turning 65 or Retiring: Leaving Employer Coverage
Leaving a job is one of the most expensive moments to get insurance wrong, whether you’re turning 65 and moving to Medicare, retiring early and bridging the years until 65, or keeping a younger spouse covered after you enroll in Medicare. The guides that apply live in two sections: the Medicare section above for anyone 65 or older, and the health insurance section for anyone who needs coverage before Medicare starts.
For the Medicare side, start with the Turning 65 Medicare Checklist and the COBRA and Medicare guide. For early retirement and spouses under 65, see the health insurance section. My Turning 65 or Retiring page explains how I help with both at once, since many households need both.
Small Business and Self-Employed Coverage
If you run a business with 50 or fewer employees, you can offer a group health plan, and carriers can’t turn your group down or raise its price because of an employee’s health history. Most carriers ask for at least one enrolled employee who isn’t the owner or the owner’s spouse, plus minimum participation and contribution rules that vary by plan. If you’re self-employed with no employees, your options are the Marketplace and off-Marketplace plans described above.
One rule surprises many owners: the size of your business changes how Medicare works for employees who turn 65. With fewer than 20 employees, Medicare generally pays first and the group plan second, so an employee who delays Part B can be left with large bills. With 20 or more, the group plan usually pays first.
Guides I’m writing for this section: how group plan participation rules work, choosing an employer contribution level, what to do when an employee turns 65, and comparing a group plan with individual coverage for a very small team. Until they’re published, my Small Business and Self-Employed page covers the essentials.
Dental, Vision, Life, and Supplemental Insurance
These plans fill the gaps a health plan leaves. Dental and vision plans cover routine care that most health plans and Original Medicare don’t, though dental plans often have waiting periods and annual maximums worth reading closely. Life insurance comes in term, which covers a set number of years, and permanent forms such as whole life, which can build cash value. Supplemental plans, such as accident, critical illness, and hospital indemnity, pay a set cash benefit after a covered event, and they work alongside a health plan, never in place of one. Supplemental insurance isn’t the same as a Medicare Supplement plan, which is a common mix-up.
Guides I’m writing for this section: how dental waiting periods and annual maximums work, term vs. permanent life insurance, whether you can get life insurance with a health condition, and what long-term care insurance covers. Until they’re published, my Dental, Vision, Life and Supplemental page covers the essentials.
Extra Help, Medicaid, and Special Situations
If your income and resources are limited, you may qualify for help that changes which plans make sense: Extra Help with Medicare drug costs, a Medicare Savings Program that helps pay Part B premiums, Medicaid alongside Medicare, or a Special Needs Plan built for people with both. Medicare isn’t only for people 65 and older, either. People under 65 who qualify because of a disability, End-Stage Renal Disease, or ALS have the same choices, and often the same help.
The Medicare guides on 2027 Part D costs and moving to Florida with Medicare cover how Extra Help and state programs fit in, and my Extra Help and Special Situations page explains eligibility in plain language.
Health Insurance Terms in Plain Language
These are the health insurance terms that come up in almost every guide and every plan review.
Premium: the monthly amount you pay to keep a plan, whether or not you use it.
Deductible: what you pay for covered care before the plan starts sharing the cost. Some plans have none.
Copay and coinsurance: your share of a visit, test, or prescription. A copay is a set dollar amount; coinsurance is a percentage.
Out-of-pocket maximum: the most you’d pay for covered care in a year. After you reach it, the plan pays in full for the rest of the year.
Network: the doctors, hospitals, and pharmacies a plan has contracts with. HMO plans usually cover only in-network care except in emergencies; PPO plans cover out-of-network care at a higher cost.
Formulary: a plan’s list of covered drugs, organized into tiers that set what you pay for each one.
Prior authorization: approval a plan requires before it covers certain services or drugs.
Open Enrollment and Special Enrollment Periods: the yearly window when anyone can enroll or change plans, and the shorter windows that open after a life change.
Creditable coverage: drug coverage that’s expected to pay at least as much as standard Medicare drug coverage. Having it protects you from a Part D late enrollment penalty.
MORE WAYS I CAN HELP
Find the Right Coverage for Every Stage of Life
Most households need more than one kind of coverage, and what you need changes as life does. Keep reading for the details on this page, or see all the coverage I help with and my guides to each type of insurance:
Frequently Asked Health Insurance Questions
Where Should I Start if I Don’t Know Which Section Applies to Me?
Start with “How Does Health Insurance Work? Start Here” above, then pick the section that matches your situation: Medicare if you’re 65 or older or qualify through a disability, health insurance under 65 if you’re buying your own plan, small business if you’re covering a team, and dental, vision, life, and supplemental for everything else. If you’re not sure, a free plan review is the fastest way to find out. I’ll ask a few questions and point you to the right coverage.
Are These Guides a Substitute for a Plan Review?
No. The guides explain how insurance works in general. Your best plan depends on your doctors, prescriptions, location, and budget, so a free plan review is the best way to apply what you’ve read to your own situation.
Are the Guides Up to Date?
Each guide shows the plan year it covers and when it was last reviewed. Deadlines, limits, and program figures change every year, and I update the guides when new rules are published. If you see something that looks out of date, call or email me and I’ll check it.
Do You Charge for Advice or Plan Reviews?
No. My help comes at no extra cost to you, and plan reviews and quotes are free with no obligation to enroll. Insurers pay my commission, and premiums are generally the same whether you enroll through me or directly with the insurance company.
Can I Use These Guides to Help a Parent or a Family Member?
Yes. Many of my clients first reach out while helping a parent with Medicare or an adult child who’s leaving their plan. With that person’s permission, I’m glad to include you in their plan review, by phone, on Zoom, or at their home in Broward, Miami-Dade, or Palm Beach.
Do You Offer Every Plan in My Area?
No. For Medicare: We do not offer every plan available in your area. Currently we represent 8 organizations which offer 65 products in your area. Please contact Medicare.gov or 1-800-MEDICARE (TTY users should call 1-877-486-2048), 24 hours a day, 7 days a week, to get information on all of your options. In Florida, you can also get free, unbiased Medicare counseling through the state’s SHIP program, called SHINE. For Marketplace plans, HealthCare.gov lists every plan available in your area, and I’ll always tell you which ones I can help you with.
Where Else Can I Get Reliable Information?
Medicare.gov and 1-800-MEDICARE for Medicare, HealthCare.gov for Marketplace plans, and the Florida Department of Financial Services for questions about any licensed agent or insurer in the state. My FAQ page answers general questions about working with me.
Book a Free Plan Review
Have a question these guides didn’t answer? Pick a time for a free 15-minute call by phone or video. I’ll check whether your doctors are covered, and my help never costs you anything extra.
Call or text: (954) 410-3710
Email: contact@chaperonehealthinsuranceplus.com
Office: 6360 NW 5th Way Ste 101, Fort Lauderdale, FL 33309
Meet by: phone, video, at my office, or at home in Broward, Miami-Dade and Palm Beach.
- How It Works
How we'll work together
Five steps, no pressure, and I stay with you after you enroll.
1
We talk about you
By phone, Zoom or face to face. Your health, your budget, your doctors.
2
I check the details
Doctors, hospitals, prescriptions and pharmacy, checked against each plan.
3
We compare real costs
A full-year estimate for each option, explained in plain language.
4
You decide, I enroll you
No pressure. If you choose a plan, I handle the application with you.
5
We review every year
Plans and networks change. I check yours each year and help with claims in between.